Top Software Companies in Seattle, WA (756)
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most - The Transaction Moment. Rokt’s AI Brain and Ecommerce Network powers billions of transactions connecting hundreds of millions of customers, and is trusted to do this by the world’s leading companies including Live Nation, Macy’s, Fanatics, AMC Theatres, PayPal, Uber, Hulu, Staples, Albertsons and...

Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as reaching about $600M with 43% year-over-year growth in 2024, with consistent references to 40%+ growth and independent estimates indicating expansion toward ~$900M annualized in 2025. This pattern is reinforced by multi‑year growth markers such as 330% revenue growth over a recent three‑year period and listings on major fast‑growth rankings.
Strong Market Position & Advantage: Scale indicators include 33,000+ companies (including more than half of leading global ecommerce brands), 165M monthly active users growing 45%+ YoY, and billions of transactions processed (7.5B+ in 2025 and 13B+ projected in 2026). High‑profile enterprise adoption across sectors (e.g., Uber, Live Nation, Macy’s, PayPal) underscores traction at the transaction moment.
Investor Backing & Capital Strength: Valuation stepped up from $2.4B (2022) to $3.5B in a January 2025 secondary transaction, alongside a prior $325M Series E and a $335M secondary, signaling sustained investor confidence. These capital events coincide with disclosures of rapid revenue growth and continued scaling.
Superhuman (formerly Grammarly) is the AI productivity platform on a mission to unlock the superhuman potential in everyone. The Superhuman suite of apps and agents brings AI wherever people work, integrating with over 1 million applications and websites. The company’s products include Grammarly’s writing assistance, Docs’ connected surface for teams, Mail’s inbox management, and Go, the proactive AI assistant that...
Superhuman's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Strategic capital is substantial, with $1B raised in 2025 to fund expansion into an AI productivity platform. This provides significant financial capacity for acquisitions and product development.
Product Line Growth: The company has broadened its footprint through acquisitions including Coda (now part of the suite), GPTZero, Rows, and Fathom, while integrating advanced AI capabilities like Superhuman Go and agent ecosystems. These moves expand the offering well beyond the original email client.
Market Expansion: Current materials cite 40M+ daily active users and 50K+ organizations, reflecting the larger Superhuman/Grammarly platform after the rebrand. Continued M&A in 2026 further extends reach into authenticity and meeting-productivity use cases.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
MORSE is a specially selected team of scientists, engineers, and software developers who use asymmetric and unconventional approaches to deploy practical solutions that solve difficult multi-disciplinary problems faced by the US National Security Ecosystem.
MORSE Corp's Top Stability & Growth Strengths
Market Expansion: The company added Arlington, VA (2024) and Seattle, WA (2025) to its Cambridge base, explicitly linking the Seattle opening to “steady growth” and proximity to customers and talent. This footprint expansion indicates broader geographic reach and increased customer access.
Innovation-Driven Growth: Large awards tied to advanced technologies—such as a ~$97.5M Army STEAM IDIQ for AI-enabled systems, a $48M Army UAS OTA, and a DARPA Albatross prime—show momentum in AI/ML, autonomy, and high-end R&D. These programs suggest growing demand for its applied engineering and experimentation capabilities.
Strong Hiring & Retention: Headcount signals moved from 150+ employees in 2022 to roughly 200+ more recently, alongside active multi-site recruiting. Workplace recognitions and the company’s description as a “thriving” employee-owned firm support continued talent attraction.
DigitalOcean is the Inference Cloud — a full-stack, production-ready cloud platform built to run AI applications with predictable performance, sustainable economics, and radically simpler operations at scale. We are built for teams turning AI into real products — not just training models. Our advantage is not fewer features, but fewer failure modes when operating AI at scale — combining minimal...

DigitalOcean's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported up 29% year over year in Q2 2026 to $281M, with ARR at $1.125B also up 29%. Guidance for 2026 was raised to about 30–31% growth alongside record incremental ARR and a sharply higher RPO.
Innovation-Driven Growth: AI-related momentum is pronounced, with AI customer ARR at $234M, up about 212% year over year, and the launch of offerings like the Inference Engine and an AI‑Native Cloud. Larger $1M+ customer ARR also surged triple-digits, indicating product-driven expansion into higher-value use cases.
Profitability: The business is described as scaling profitably, posting strong net income and robust adjusted EBITDA margins while growing. Management commentary highlights continued profitable expansion even as investment in AI and capacity ramps.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Profitability: Adjusted EBITA and margins improved markedly in 2025, with adjusted EBITA rising from SEK 27.2B to SEK 42.9B and margin from 11.0% to 18.1%. Margin resilience continued into 2026 despite mixed sales.
Resilient & Sustainable Growth: Underlying sales show modest improvement, with +6% organic growth in Q1 2026 and +2% for H1 2026. Organic growth also appeared in three of four market areas in Q2 2026.
Healthy Cash Flow: Cash generation remained positive, with H1 2026 free cash flow before M&A up year over year. Net cash strengthened versus the prior year, supporting financial flexibility.
Artera is a patient communication and engagement platform designed to assist healthcare providers in managing and automating interactions with patients through various channels, including text, email, phone, and voice AI agents. This innovative solution caters to a diverse range of healthcare entities, such as specialty practices, Federally Qualified Health Centers (FQHCs), health systems, and federal agencies, all of which require...

Artera's Top Stability & Growth Strengths
Strong Revenue Growth: Reported $100M in contracted annual recurring revenue by the end of 2025 and a high placement on Deloitte’s Technology Fast 500 together indicate substantial multi‑year expansion.
Investor Backing & Capital Strength: A $65M growth investment led by established firms signals strong access to capital and confidence in the company’s expansion plans.
Strong Market Position & Advantage: Recognition as #1 Best in KLAS for Patient Communications in 2026 and adoption across 1,000+ healthcare organizations reflect meaningful category standing.

Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Cash App gross profit has risen strongly over multiple periods, with momentum attributed to growth in Borrow, BNPL products, and the Cash App Card. Company communications indicate continued year-over-year expansion that has supported raised outlooks.
Diversified Revenue Streams: Multiple monetization pillars—consumer lending, card spend/commerce enablement, banking features, and payments—are contributing to growth, while Bitcoin-related revenue has relatively little impact on gross profit. Excluding Bitcoin, segment net revenue growth has been materially stronger, and per-active monetization has increased.
Strong Market Position & Advantage: The platform has built a very large transacting active base and ranks near the top of U.S. finance app downloads, supporting scale-driven advantages. Engagement indicators such as inflows per active and primary banking adoption have increased, signaling deepening usage.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
SentiLink is the leading fraud intelligence company, providing financial institutions and fintechs with purpose-built solutions for identity verification and fraud prevention. Our products detect synthetic fraud, identity theft, and hard-to-detect first-party fraud in real time — helping partners stop losses before they happen while approving more legitimate customers. Founded in 2017 by Naftali Harris and Max Blumenfeld, creators of the risk...

SentiLink's Top Stability & Growth Strengths
Market Expansion: Public materials indicate expansion from serving 100+ organizations in 2022 to 400+ institutions by 2025, including moves into telecom and government with FedRAMP Ready status enabling federal opportunities. Evidence also points to deeper enterprise reach, including 11 of the 15 largest U.S. banks and 6 of the top 10 credit unions.
Product Line Growth: The offering has broadened from synthetic identity fraud into identity theft, first‑party fraud, and a CIP/KYC suite (e.g., CIP Match & Watchlists), later adding analyst tooling like Intercept. These additions expand addressable use cases across financial services and adjacent verticals.
Strategic Partnerships: Ecosystem ties include a FICO Industry Vanguard Decision Award with direct integration of SentiLink’s Identity Theft Score into the FICO Marketplace, alongside collaborations such as Yardi, Taktile, and a state‑level selection by Florida’s AHCA. These channels and validations open distribution and reinforce product relevance with large enterprises.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...
Dropbox's Top Stability & Growth Strengths
Profitability: Profitability is depicted as strong, with non-GAAP operating margins near 40% and improved GAAP net income. Feedback suggests this strength persists even amid slow top-line growth.
Healthy Cash Flow: Cash generation is highlighted as substantial, including FY2025 free cash flow above $1B and significant unlevered free cash flow in Q2 2026. Feedback suggests robust cash flow supports buybacks and financial flexibility.
Resilient & Sustainable Growth: Core operations are portrayed as stabilizing in 2026 with low single-digit revenue and ARR growth excluding FormSwift. Feedback suggests paying users have resumed modest sequential increases, indicating resilience.
Vannevar combines Silicon Valley innovation with former special operators to build AI for real-world national security outcomes. Since our founding in 2019, Vannevar has deployed its technology across 125 missions, safeguarding our service members and improving our country's deterrence. We believe our military service members and intelligence officers deserve access to the best technology American innovation can offer, and we are...

Vannevar's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising from about $3.5M in 2021 to roughly $80M in 2024, with annual contract value also increasing substantially. Feedback suggests this momentum reflects rapid scaling of contracted business.
Profitability: The company is reported to have become profitable within three years and to have maintained profitability thereafter. This points to efficient scaling rather than reliance solely on external financing.
Market Expansion: Contracting progressed from prototypes to a DIU production vehicle with a $99M ceiling, followed by additional Air Force and OSD awards through 2025–26. The stated footprint grew to about 125 deployments across every service branch and combatant command.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins expanded, with Q2 2026 EBITDA up 30% year over year and margin improving to 37%, alongside higher net income. This pattern indicates operating leverage as earnings outpace the top line.
Strong Revenue Growth: Revenue rose 7% in 2025 and accelerated to 11% year over year in Q2 2026, with multiple sequential quarters showing improving trends. The recent trajectory points to faster growth rather than a flat profile.
Healthy Cash Flow: Free cash flow is guided to grow at more than 30% for 2026 and was later raised to the high-40% range, while Q2 2026 generated $57.4M in operating cash. Debt reduction in 1H 2026, including repayment of $205M in convertibles, further supports balance-sheet strength.
We are building AI to simulate the world through merging art and science. We believe that world models are at the frontier of progress in artificial intelligence. Language models alone won't solve the world’s hardest problems – robotics, disease, scientific discovery. Real progress requires models that experience the world and learn from their mistakes, the same way that humans do. And...
Runway's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $315M Series E in February 2026 at a reported ~$5.3B valuation signals substantial resources to scale compute and R&D. Late‑stage investor confidence and expanded compute partnerships indicate capacity to sustain momentum.
Strategic Partnerships: Studio and enterprise relationships—such as Lionsgate’s preferred partner designation and expansion, plus ties with AMC, Adobe, Bertelsmann, and MIXI—embed Runway in professional workflows. These alliances reinforce distribution, credibility, and commercial adoption.
Innovation-Driven Growth: Successive model releases (Gen‑3 → Gen‑4 → Gen‑4.5), an expanding API, and a roadmap toward “General World Models” reflect a sustained R&D cadence that ships into creator‑friendly tools. Consistent commercial availability and updates make advances usable in real production contexts.
DMC is an established project-based engineering and software development firm founded in 1996 and based in Chicago, Illinois. We develop and implement solutions for a wide range of industries using a variety of technologies. Every solution we develop is based upon a solid understanding of software and system integration principles. DMC maintains premier technology partnerships with Microsoft, Siemens, and National...
The future of the automotive industry is in connectivity, software, and services – and Autonomic is leading the charge. Autonomic created the Transportation Mobility Cloud (TMC) to provide automakers and developers with the first cloud platform specifically designed for the world’s automotive industry. Working closely with Ford Motor Company, we are combining the best of both worlds – Autonomic’s progressive...
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
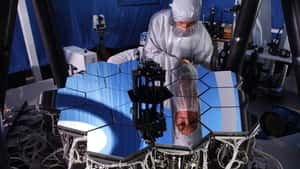
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.