

Top Tech Companies in Seattle, WA (3,153)
MORSE is a specially selected team of scientists, engineers, and software developers who use asymmetric and unconventional approaches to deploy practical solutions that solve difficult multi-disciplinary problems faced by the US National Security Ecosystem.
MORSE Corp's Top Stability & Growth Strengths
Market Expansion: The company added Arlington, VA (2024) and Seattle, WA (2025) to its Cambridge base, explicitly linking the Seattle opening to “steady growth” and proximity to customers and talent. This footprint expansion indicates broader geographic reach and increased customer access.
Innovation-Driven Growth: Large awards tied to advanced technologies—such as a ~$97.5M Army STEAM IDIQ for AI-enabled systems, a $48M Army UAS OTA, and a DARPA Albatross prime—show momentum in AI/ML, autonomy, and high-end R&D. These programs suggest growing demand for its applied engineering and experimentation capabilities.
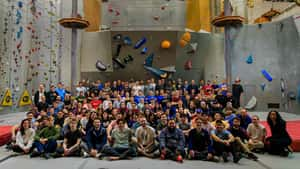
Strong Hiring & Retention: Headcount signals moved from 150+ employees in 2022 to roughly 200+ more recently, alongside active multi-site recruiting. Workplace recognitions and the company’s description as a “thriving” employee-owned firm support continued talent attraction.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
SoFi wasn’t built to be a bank. Or a technology company. We were built for one mission: help people achieve financial independence so they can realize their ambitions. Redefining an entire industry isn’t easy work—and it’s not for the faint of heart. It takes a certain kind of team. People with diverse perspectives and expertise, united by a common sense of...
SoFi's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding rapidly, with record quarterly net revenue and management raising full-year 2026 revenue guidance amid broad-based growth across members, products, and loan originations. Q2 2026 GAAP and adjusted revenue increased sharply year over year, indicating continued top-line momentum.
Profitability: GAAP net income has turned and remained positive alongside rising adjusted EBITDA, suggesting operating leverage as the business scales. Q2 2026 reported meaningful net income and near-30% EBITDA margins.
Diversified Revenue Streams: Fee-based lines and the Financial Services segment are scaling quickly, reducing reliance on traditional lending. 2025 saw fee-based revenue surge and the Technology Platform contribute hundreds of millions of dollars, pointing to a broader mix.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Cash App gross profit has risen strongly over multiple periods, with momentum attributed to growth in Borrow, BNPL products, and the Cash App Card. Company communications indicate continued year-over-year expansion that has supported raised outlooks.
Diversified Revenue Streams: Multiple monetization pillars—consumer lending, card spend/commerce enablement, banking features, and payments—are contributing to growth, while Bitcoin-related revenue has relatively little impact on gross profit. Excluding Bitcoin, segment net revenue growth has been materially stronger, and per-active monetization has increased.
Strong Market Position & Advantage: The platform has built a very large transacting active base and ranks near the top of U.S. finance app downloads, supporting scale-driven advantages. Engagement indicators such as inflows per active and primary banking adoption have increased, signaling deepening usage.
Since 2011, Remitly has been tirelessly delivering on our promises to our customers sending their hard earned money home. Today, we are incredibly proud to have served millions of customers globally. We strive daily to meet our promise to our customers by building peace of mind into everything we do. Join over 2,700 employees across 10 offices who are growing...
Remitly's Top Stability & Growth Strengths
Strong Revenue Growth: Recent disclosures show sustained top-line momentum, with quarterly revenue around $495M and full-year guidance raised to nearly $2B. This trajectory follows a prior year with revenue of about $1.64B and continued growth into 2026.
Profitability: Operating results highlight a shift to positive GAAP net income in 2025 and materially higher adjusted EBITDA in 2026. This indicates improving operating leverage alongside expansion in customers and send volume.
Product Line Growth: Offerings are expanding beyond core remittances with the Global Card, wallet features (including USDC capabilities), business remittances, and “Send Now, Pay Later.” These additions broaden the addressable market and create new monetization avenues.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
Who We Are Chewy is where pet parents find everything they need for life with pets, from food to fun to pharmacy. We make pet care easier, more informed, and more joyful through fast, reliable delivery and award-winning 24/7 Customer Care, including access to pet health support when it’s needed. Founded in 2011, Chewy combines the convenience of online shopping with...

Chewy's Top Stability & Growth Strengths
Customer Loyalty & Retention: Autoship accounts for the vast majority of sales (over four-fifths) and is growing faster than total revenue, indicating a sticky, recurring base and higher retention. Evidence includes Autoship representing ~83% of FY2025 net sales and ~84.6% in Q2 FY2026 with high single‑digit to double‑digit growth.
Profitability: Operating metrics show expanding earnings power, with adjusted EBITDA up materially and margins improving alongside strong free cash flow. Observations include FY2025 adjusted EBITDA growth of ~26% with margin expansion and additional year‑over‑year gains reported in 1H FY2026.
Strong Market Position & Advantage: Chewy is characterized as the largest U.S. pet e‑tailer and a leading online pet‑supplies platform by GMV and digital presence, underpinning durable scale advantages. Multiple summaries highlight leadership in online pet retail, substantial Autoship penetration, and strong digital search share versus specialty peers.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Profitability: Adjusted EBITA and margins improved markedly in 2025, with adjusted EBITA rising from SEK 27.2B to SEK 42.9B and margin from 11.0% to 18.1%. Margin resilience continued into 2026 despite mixed sales.
Resilient & Sustainable Growth: Underlying sales show modest improvement, with +6% organic growth in Q1 2026 and +2% for H1 2026. Organic growth also appeared in three of four market areas in Q2 2026.
Healthy Cash Flow: Cash generation remained positive, with H1 2026 free cash flow before M&A up year over year. Net cash strengthened versus the prior year, supporting financial flexibility.
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Observability revenues are described as rising sharply across consecutive years, with ThousandEyes repeatedly identified as a primary contributor to that momentum. Growth continued thereafter even as the broader category’s pace moderated, indicating durable contribution from ThousandEyes.
Market Expansion: ThousandEyes has been embedded into Cisco’s Digital Experience Assurance and extended across enterprise networks, the public Internet, SaaS, and public-cloud environments. Customer penetration among large enterprises has increased materially since FY2020, signaling broader reach and adoption.
Product Line Growth: Cisco has continued to add capabilities such as Cloud Insights and Traffic Insights while integrating data from Meraki and Catalyst. These enhancements expand use cases beyond standalone monitoring toward end‑to‑end network assurance.

SentiLink is the leading fraud intelligence company, providing financial institutions and fintechs with purpose-built solutions for identity verification and fraud prevention. Our products detect synthetic fraud, identity theft, and hard-to-detect first-party fraud in real time — helping partners stop losses before they happen while approving more legitimate customers. Founded in 2017 by Naftali Harris and Max Blumenfeld, creators of the risk...

SentiLink's Top Stability & Growth Strengths
Market Expansion: Public materials indicate expansion from serving 100+ organizations in 2022 to 400+ institutions by 2025, including moves into telecom and government with FedRAMP Ready status enabling federal opportunities. Evidence also points to deeper enterprise reach, including 11 of the 15 largest U.S. banks and 6 of the top 10 credit unions.
Product Line Growth: The offering has broadened from synthetic identity fraud into identity theft, first‑party fraud, and a CIP/KYC suite (e.g., CIP Match & Watchlists), later adding analyst tooling like Intercept. These additions expand addressable use cases across financial services and adjacent verticals.
Strategic Partnerships: Ecosystem ties include a FICO Industry Vanguard Decision Award with direct integration of SentiLink’s Identity Theft Score into the FICO Marketplace, alongside collaborations such as Yardi, Taktile, and a state‑level selection by Florida’s AHCA. These channels and validations open distribution and reinforce product relevance with large enterprises.
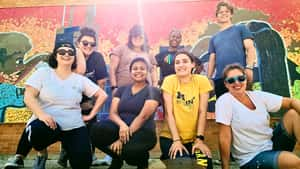
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring and headcount are expanding, with disclosures of 15,000+ global employees, thousands of new hires, and third‑party estimates indicating continued workforce growth. Available evidence also points to active internal mobility and a recent increase in active job postings.
Market Expansion: Geographic and client footprints are broadening, with 40+ offices and 1,700+ customers across 170+ countries alongside concrete investments in new and expanded locations such as Hyderabad and Kingston. These moves indicate scaling delivery capacity in major capability centers and new regions.
Innovation-Driven Growth: The offering mix is shifting toward AI, data, technology, and platforms, including proprietary solutions and product capabilities. Strategic moves such as Salesforce-focused acquisitions and collaborations, plus a Tulip solution partnership, extend capabilities beyond traditional consulting.
Build what’s next — with tech that matters PwC provides professional services across Audit and Assurance, Advisory and Tax — powered by a global network of over 370,000 people in 149 countries. You may know us for our business expertise, but technology is core to how we help clients move faster, build trust and deliver meaningful outcomes. As a technologist, you’ll work...

PwC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue has increased year over year to a new high, with all three major service lines posting gains despite a slower pace. Growth remains uneven by region, but the overall trajectory is upward over the last several fiscal years.
Future-Ready Strategy: Multi‑billion‑dollar investments in technology—especially nearly $1.5B in AI—along with acquisitions and scaling managed services indicate a deliberate pivot to future growth levers. Leadership attention to next‑generation audit and AI‑enabled capabilities underscores preparation for emerging demand.
Strong Market Position & Advantage: The organization is characterized as a leading global professional‑services network with broad scale across assurance, advisory, and tax and repeated external recognitions in select consulting categories. Reach across major multinational clients supports durable competitive positioning.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins expanded, with Q2 2026 EBITDA up 30% year over year and margin improving to 37%, alongside higher net income. This pattern indicates operating leverage as earnings outpace the top line.
Strong Revenue Growth: Revenue rose 7% in 2025 and accelerated to 11% year over year in Q2 2026, with multiple sequential quarters showing improving trends. The recent trajectory points to faster growth rather than a flat profile.
Healthy Cash Flow: Free cash flow is guided to grow at more than 30% for 2026 and was later raised to the high-40% range, while Q2 2026 generated $57.4M in operating cash. Debt reduction in 1H 2026, including repayment of $205M in convertibles, further supports balance-sheet strength.
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with H1 2026 up 11% and Q1/Q2 growing 14% and 8% respectively, supported by higher commercial-aircraft deliveries. This momentum reflects increased production throughput and broader top-line recovery.
Healthy Cash Flow: Cash generation is improving, as H1 2026 operating cash flow turned positive and free cash flow improved, including a positive result in Q2. This shift indicates better working-capital dynamics alongside rising delivery volume.
Strong Market Position & Advantage: Backlog is at a record level of roughly $715 billion, including more than 6,200 commercial aircraft. This depth of contracted demand provides multi‑year visibility for production and revenue.
Our Mission: Create a world where everyone has an authentic digital identity. Identity Digital is an internet infrastructure company that makes sure web addresses work seamlessly. If we do our job right, we are invisible to the user. We have the world’s largest portfolio of nearly 300 TLDs like .info, .pro, .world, which lets people and businesses build, market, and own...
Identity Digital's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the Inc. 5000 for five consecutive years and company statements of “healthy revenue growth” in 2025 indicate sustained top-line expansion. Three-year growth figures cited for recent periods (e.g., 152% then 82%) reinforce momentum, even though audited financials are not public.
Market Expansion: The .ai migration and subsequent surge (more than 60% YoY registrations in 2025, with registrar distribution roughly doubling) alongside multiple 2025 registry-agreement changes point to a growing footprint. Access to 1,800+ ICANN-accredited registrars and operations across 80+ locations further extend reach.
Strong Market Position & Advantage: Operating what is described as nearly 300 TLDs and supporting 28M+ domains, while resolving 60.4B+ DNS queries per day, signals substantial scale. Broad registrar access (including 90%+ coverage for .ai at migration) and a large installed base underscore competitive advantage.
DoubleDown Interactive is a leading developer and publisher of digital games on mobile and web-based platforms. We are the creators of multi-format interactive entertainment experiences for casual players, bringing authentic Vegas entertainment to players around the world through an online social casino experience. Our flagship social casino title, DoubleDown Casino, has been a fan-favorite game on leading social and mobile...
DoubleDown Interactive LLC's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising, with the latest quarters showing year-over-year increases and 2026 momentum described as accelerating. Q4 2025 and the first half of 2026 point to sustained top-line expansion across social casino and iGaming.
Profitability: Profit and adjusted EBITDA increased notably in recent quarters, and full-year EBITDA remained high across 2023–2025. The most recent results indicate profitability expanding faster than revenue.
Diversified Revenue Streams: Direct-to-Consumer revenue expanded sharply and became a much larger share of social-casino sales, while SuprNation and the WHOW Games acquisition added incremental contribution. These shifts reduce reliance on legacy channels and broaden where growth can come from.
It’s curious to think of innovation and stability co-existing. But we pair a 100-year track record of success with a hunger to do things differently. Everyone is in the work — tackling complex problems where your impact can build back or build up the communities we serve. We fill our halls with curious minds from all walks of life. Our...
Lowe’s's Top Stability & Growth Strengths
Strong Revenue Growth: Total sales rose to $26.0B in Q2 FY2026 from $24.0B (+8.3%) and to $23.1B in Q1 from $20.9B, with full‑year sales guided to about $92B. Growth has been supported by Pro customers, home services, and double‑digit online gains even as comparable sales stayed modest.
Market Expansion: Acquisitions of Foundation Building Materials and Artisan Design Group, along with a slightly larger footprint, have expanded reach and lifted reported sales. Management also notes five consecutive quarters of positive comparable sales, indicating incremental traction across the base.
Future-Ready Strategy: The Total Home strategy emphasizes Pro, e‑commerce, and services, with online sales up ~15–16% in Q1/Q2 FY2026. Omnichannel and technology investments are helping sustain momentum in channels outperforming a softer DIY backdrop.
2K is headquartered in Novato, California and is a wholly owned label of Take-Two Interactive Software, Inc. (NASDAQ: TTWO). Founded in 2005, 2K Games is a global video game company, publishing titles developed by some of the most influential game development studios in the world. Our studios responsible for developing 2K’s portfolio of world-class games across multiple platforms, include Visual...
2K's Top Stability & Growth Strengths
Strong Revenue Growth: Take-Two’s FY2026 disclosures show year-over-year increases in revenue and net bookings, with NBA 2K and Borderlands among the largest contributors. The filing attributes $416.9M of incremental revenue to NBA 2K and $210.3M to Borderlands, both published by 2K.
Diversified Revenue Streams: Multiple 2K franchises and live-service monetization contributed to top-line expansion rather than relying solely on initial sales. Company materials note rising recurrent consumer spending led primarily by NBA 2K, alongside contributions from WWE 2K and Borderlands.
Product Line Growth: 2K’s active slate features NBA 2K27, WWE 2K26, Borderlands 4, Mafia: The Old Country, Civilization VII, and other titles listed on its store. Newsroom updates through September 2026 highlight ongoing releases and post-launch content across these franchises.

Our purpose ensures that patients remain at the center of all we do. We live our purpose by sourcing the best science in the world; partnering with others in the healthcare system to improve access to our medicines; using digital technologies to enhance our drug discovery and development, as well as patient outcomes; and leading the conversation to advocate for...

Pfizer's Top Stability & Growth Strengths
Product Line Growth: Growth in medicines such as Eliquis, Padcev, the Vyndaqel family, Lorbrena, Nurtec/Vydura and oncology biosimilars more than offset part of the COVID-related decline in the first half of 2026. Launched and acquired products also delivered strong double‑digit operational gains in Q2 2026.
Resilient & Sustainable Growth: Underlying revenue excluding COVID products advanced at a mid‑single‑digit pace in 2025 and the first half of 2026, while total revenue returned to modest year‑over‑year growth in early 2026. Management raised the midpoint of 2026 revenue guidance, signaling improving momentum beneath headline totals.
Future-Ready Strategy: Heavy investment in a broad late‑stage pipeline and plans for numerous pivotal study starts in 2026 support longer‑term growth. Continued business development and integration of acquired assets are positioned to offset COVID normalization and loss‑of‑exclusivity pressures over time.
T-Mobile U.S. Inc. (NASDAQ: TMUS) is America’s supercharged Un-carrier, delivering an advanced 4G LTE and transformative nationwide 5G network that will offer reliable connectivity for all. T-Mobile’s customers benefit from its unmatched combination of value and quality, unwavering obsession with offering them the best possible service experience and undisputable drive for disruption that creates competition and innovation in wireless and...
T-Mobile's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and service revenue are rising across 2025 and into 2026, with postpaid service revenue outpacing the overall top line. Quarterly updates indicate momentum continued with further gains in service revenue and ARPA.
Healthy Cash Flow: Operating cash flow and adjusted free cash flow increased, indicating that top-line growth is converting into cash generation. Recent quarters also showed year-over-year gains in free cash flow alongside higher Core Adjusted EBITDA.
Market Expansion: The customer base is expanding through continued postpaid account additions and growth in home broadband, while acquisitions such as UScellular’s wireless operations broaden reach. Added accounts alongside higher ARPA point to organic expansion within core markets and adjacencies.



