Top Cloud Companies in Seattle, WA (180)
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased over recent fiscal years, with the latest results showing faster top-line momentum. Cloud sales expanded more quickly than the overall business, reinforcing this trajectory.
Customer Loyalty & Retention: Net revenue retention above 100% and rising subscription ARR indicate existing customers are expanding spend and renewing at healthy levels. Growth in higher-value cloud cohorts and larger contracted obligations add visibility.
Innovation-Driven Growth: Expansion into AI-assisted teamwork and enterprise service management is driving additional adoption and cross-sell alongside core products. Early traction for offerings like Rovo suggests multiple vectors beyond new-customer acquisition.
Monte Carlo is the agent trust platform that unifies data and agent observability to monitor, troubleshoot, and improve production AI systems. As enterprises prepare to deploy thousands of agents across business-critical use cases, Monte Carlo provides the reliability infrastructure to support them along this AI transformation, from human-guided agents to fully autonomous operations. Founded 2019. Backed by leading investors. Trusted...

Monte Carlo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The company secured a $135 million Series D in 2022, bringing total funding to $236 million and a reported billion-plus valuation. This capital base supports continued investment in product and market initiatives.
Strong Market Position & Advantage: The company reports more than 400 enterprise customers, including PepsiCo, Cisco, Nasdaq, Roche, and The New York Times. This breadth points to meaningful enterprise adoption and commercial scale.
Product Line Growth: The platform has expanded from data observability into AI reliability and agent observability, monitoring AI agents in production alongside underlying data pipelines. Company-reported usage metrics—such as 10 million tables monitored and 1,000 incidents resolved daily—indicate a growing product footprint.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 38% year over year to $427.3M in Q2 FY2027, with subscription revenue up 37% and subscription ARR up 33% to $1.66B. Enterprise adoption is also rising, with customers generating at least $100K in subscription ARR growing from 2,505 to 3,084 year over year.
Healthy Cash Flow: Free cash flow was positive at $65.7M in Q2 FY2027, up from $57.5M a year earlier. Operating leverage is improving as subscription ARR contribution margin increased to 14.0% from 9.4%.
Investor Backing & Capital Strength: Liquidity is substantial, with $1.75B in cash, cash equivalents and short‑term investments as of July 31, 2026. This balance sheet capacity provides flexibility to fund continued growth and execution.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
Hiya is trusted by global businesses, carriers, and consumers to enable secure, engaging connections and stop unwanted calls. Hiya is pioneering the next generation of AI-powered voice intelligence with real-time analysis and an AI assistant to enhance voice protection, productivity, and call performance. Hiya connects businesses with their customers, helps carriers secure their networks, and protects people from spam and...
Hiya Inc.'s Top Stability & Growth Strengths
Market Expansion: International rollouts with major carriers in France, Sweden, Finland, the UK, and Germany, alongside coverage in 40+ countries and 550M+ people reached, point to broadening geographic presence and adoption. These developments signal accelerating distribution through network-level deployments rather than relying solely on standalone apps.
Strategic Partnerships: Multi-year agreements and new deployments with Samsung (extended through 2028) and operators such as Deutsche Telekom, O2 Telefónica, Vodafone, Bouygues Telecom, Telenor, and DNA indicate durable enterprise relationships. These tie-ups embed the platform at the carrier and device level, supporting continued commercial traction.
Product Line Growth: Expansion beyond spam detection into AI voice security, deepfake detection, branded calling, and tools like Caller Reputation and Hiya AI Phone broadens monetization paths. The Loccus.ai acquisition and subsequent feature launches illustrate ongoing investment in new capabilities.
CoreWeave, the AI Hyperscaler™, delivers a cloud platform of cutting-edge software powering the next wave of AI. The company's technology provides enterprises and leading AI labs with cloud solutions for accelerated computing. Since 2017, CoreWeave has operated a growing footprint of data centers across the US and Europe. CoreWeave was ranked as one of the TIME100 most influential companies and...

CoreWeave's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded from roughly $1.9B in 2024 to $5.1B in 2025, with mid-2026 quarterly revenue still rising sharply. A very large revenue backlog of about $104B and additional net new commitments point to continued demand.
Strong Market Position & Advantage: The company is described as a leading specialist in AI-focused cloud infrastructure, supported by major contracts and third-party recognition. This advantage is reinforced by large-scale GPU capacity and adoption across AI labs, hyperscalers, and enterprises.
Strategic Partnerships: Relationships with NVIDIA and multiyear agreements with organizations such as Meta and Anthropic underpin access to advanced hardware and sizeable workloads. These alliances appear to support capacity build-out and commercial visibility.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has been accelerating on a quarterly basis, and full-year guidance was raised, reflecting sustained top-line momentum. Contracted demand indicators also point to continued near-term growth.
Market Expansion: Enterprise penetration is deepening with record additions of large customers and a notable footprint among major corporate ecosystems and top global websites. The customer mix is shifting upmarket, signaling successful movement into higher-value segments.
Innovation-Driven Growth: Adoption of Workers, Zero Trust, and AI-related workloads is highlighted as a key catalyst expanding use of the platform. Product breadth across security, developer services, and edge computing is supporting multi-product growth.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Healthy Cash Flow: Cash generation is described as substantial, with unlevered free cash flow of about $1.016B in 2025 and $283.5M in Q2 2026, indicating strong cash-producing ability despite modest top-line growth.
Profitability: Margins are portrayed as strong, with a 40.6% non-GAAP operating margin in 2025 and near 40% in Q2 2026, reflecting disciplined cost management and efficient operations.
Resilient & Sustainable Growth: Feedback suggests core revenue excluding FormSwift has returned to slight year-over-year growth and paying users have increased for several consecutive quarters, pointing to stabilization and incremental expansion.

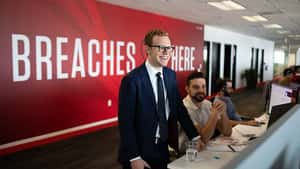
CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 26% year over year to about $1.47B in Q2 FY2027, while ARR increased roughly 25% to $5.84B and the full‑year outlook was raised. These indicators point to durable top‑line momentum across recent quarters and fiscal years.
Healthy Cash Flow: Quarterly free cash flow increased to about $377M (from ~$284M a year earlier) and operating cash flow reached roughly $530M. Rising cash generation alongside growth supports operating flexibility and investment capacity.
Product Line Growth: Adoption across the Falcon platform is deepening, with record net new ARR of about $333M (+51% YoY) and rapid expansion in offerings such as Falcon Flex ARR (exceeding ~$2.29B, up ~101% YoY). Cloud and identity security ARR also expanded meaningfully, indicating broader portfolio traction.

DigitalOcean is the Inference Cloud — a full-stack, production-ready cloud platform built to run AI applications with predictable performance, sustainable economics, and radically simpler operations at scale. We are built for teams turning AI into real products — not just training models. Our advantage is not fewer features, but fewer failure modes when operating AI at scale — combining minimal...

DigitalOcean's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with Q2 2026 sales of $281M up strongly year over year and management lifting its 2026 outlook toward roughly $1.17–$1.18B.
Innovation-Driven Growth: AI-related demand is expanding rapidly, with AI customer ARR reaching $234M and million‑dollar‑plus customer ARR also surging.
Healthy Cash Flow: Operating performance remains solid, as adjusted EBITDA reached $114M in Q2 2026 and prior filings highlighted sustained positive free‑cash‑flow generation.
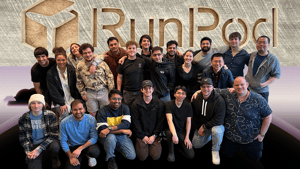
Runpod is pioneering the future of AI and machine learning, offering cutting-edge cloud infrastructure for full-stack AI applications. Founded in 2022, we are a rapidly growing, well-funded company with a remote-first organization spread globally. Our mission is to empower innovators and enterprises to unlock AI's true potential, driving technology and transforming industries. Join us as we shape the future of...
Runpod's Top Stability & Growth Strengths
Strong Revenue Growth: Reported annual recurring revenue rose from $120M in January 2026 to over $325M by October 2026, indicating rapid top-line momentum. Independent business reporting also described a mid‑year doubling to about $240M annualized revenue, reinforcing the pace of expansion.
Investor Backing & Capital Strength: A $100 million growth investment led by Summit Partners at a reported $1 billion valuation provides additional resources and signals institutional confidence. This capital is positioned to fund platform expansion, engineering, and global access.
Market Expansion: The platform expanded GPU availability and geographic reach, citing operations across 31+ regions and new regional capacity. Enterprise adoption and billions of serverless inference requests suggest deeper workload penetration beyond low‑cost rentals.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue each rose 25% in fiscal 2026, with fourth-quarter revenue also up 25% year over year. Management still expects continued double-digit growth in fiscal 2027, albeit at a slower pace.
Healthy Cash Flow: Operating cash flow reached about $1.13 billion and free cash flow was roughly $779.1 million in fiscal 2026. This points to robust cash generation alongside expansion.
Product Line Growth: The platform is expanding into AI security, data security, SASE, and agentic security operations. Security-for-AI bookings were reported to increase more than 50% sequentially in the fourth quarter, indicating early traction.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising at a strong, double‑digit pace across recent quarters and years, with subscription sales increasing alongside total revenue. Company guidance for subscription revenue was raised, reinforcing the momentum.
Resilient & Sustainable Growth: Remaining performance obligations and current contracted revenue expanded, indicating meaningful visibility into future sales. Growth in large enterprise customers and multi‑million‑dollar deals further supports durability.
Innovation-Driven Growth: AI offerings became a meaningful commercial driver as ServiceNow AI exceeded $1 billion in annual contract value and deployments accelerated. Adoption of workflow and AI products is highlighted as a primary catalyst.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests quarterly reported sales and organic growth have recently improved, led by the Networks business with 7% organic growth in Q3 2026 and a 6% increase in reported sales to SEK 59.5B. Underlying momentum is also visible year-to-date with 4% organic sales growth through September 2026 despite currency and portfolio effects.
Cost & Operational Efficiency: Feedback suggests margins and efficiency have seen progress, with adjusted gross margin near prior-year levels and prior-year improvements in adjusted EBITA and gross margin indicating disciplined execution. This operational resilience supports stability even when headline revenue is uneven.
Strong Market Position & Advantage: Feedback suggests Ericsson retains a strong competitive footing in mobile network infrastructure, with Networks as a clear growth engine across regions like Japan, India, Vietnam, and the Middle East. The company is viewed as a leading vendor in 5G RAN and core markets, underpinning demand durability.
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Cisco’s filings indicate its Observability category is expanding, with ThousandEyes explicitly cited as a contributor to that growth. More recent updates also describe year-over-year increases for the category, reinforcing ThousandEyes’ positive revenue impact.
Product Line Growth: Ongoing releases such as AI-enabled workflows, Traffic Insights, and deeper integrations (including with Splunk) broaden ThousandEyes’ capabilities. Additions like Connected Devices and expanded cloud visibility move the product beyond traditional network monitoring into wider assurance use cases.
Market Expansion: ThousandEyes is being extended across Cisco’s ecosystem and into service-provider scenarios, increasing its reach beyond conventional enterprise IT teams. Expanded distribution through Cisco networking and observability portfolios creates additional cross-sell pathways.
SPR is a technology modernization firm that helps organizations build and modernize complex systems. It develops custom software and mobile applications and provides AI, data analytics, and cloud expertise. SPR works alongside client teams to design, engineer, integrate, test, deploy, and support solutions tailored to business needs, aiming to improve customer experience, efficiency, and growth.

BitTitan® empowers IT service professionals to successfully deploy and manage cloud technologies through automation. MigrationWiz® is the industry-leading SaaS solution for mailbox, document, public-folder, and Teams migrations between a wide range of Sources and Destinations. Voleer is a solution that centralizes and automates IT tasks, helping empower IT service professionals to streamline daily operations and reduce redundancies. Since 2009, BitTitan...

More than 1,000 top employers trust Bright Horizons® (NYSE: BFAM) for proven solutions that support employees, advance careers, and maximize performance. From on-site child care that amplifies your culture, back-up care to handle disruptions, and education programs that build critical skills, our services help families achieve more.

Bright Horizons's Top Stability & Growth Strengths
Strong Market Position & Advantage: Bright Horizons is positioned as a category leader in employer-sponsored child care and back-up care, supported by its scale and enterprise-grade delivery model. The combination of a large global center network and deep employer relationships is framed as a competitive moat in its core niche.
Strong Revenue Growth: Revenue and earnings are described as rising year over year, with continued top-line expansion guided for the next year. Growth is repeatedly attributed to stronger utilization and demand across key offerings, indicating sustained commercial momentum.
Diversified Revenue Streams: The business spans full-service centers, back-up care, and education advisory offerings, creating multiple demand drivers across life stages and use cases. This mix is presented as helping smooth cycles and support steadier performance versus single-service providers.

InConsulting Inc. is a non-traditional IT consulting and recruiting firm that specializes in AI consulting services. They empower businesses through AI, cloud, automation, and diverse tech talent to drive innovation and growth. The company provides end-to-end technology consulting, staffing services, and placement solutions, focusing on transforming complex data into actionable strategies that result in smarter, data-driven decisions.