

Top Tech Companies in Seattle, WA (3,138)
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.
Artera is a patient communication and engagement platform designed to assist healthcare providers in managing and automating interactions with patients through various channels, including text, email, phone, and voice AI agents. This innovative solution caters to a diverse range of healthcare entities, such as specialty practices, Federally Qualified Health Centers (FQHCs), health systems, and federal agencies, all of which require...

Artera's Top Stability & Growth Strengths
Strong Revenue Growth: Reported $100M in contracted annual recurring revenue by the end of 2025 and a high placement on Deloitte’s Technology Fast 500 together indicate substantial multi‑year expansion.
Investor Backing & Capital Strength: A $65M growth investment led by established firms signals strong access to capital and confidence in the company’s expansion plans.
Strong Market Position & Advantage: Recognition as #1 Best in KLAS for Patient Communications in 2026 and adoption across 1,000+ healthcare organizations reflect meaningful category standing.
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose at double‑digit rates in 2025 and continued to increase at a similar pace in early 2026, supported by higher gross dollar volume, cross‑border activity, and switched transactions. The multi‑quarter trend indicates consistent top‑line momentum rather than a one‑off spike.
Profitability: Operating income outpaced revenue growth in 2025, expanding margins, while net income and EPS also advanced strongly. This points to operating leverage as volumes and higher‑yield cross‑border flows scale.
Diversified Revenue Streams: Value‑added services and solutions grew markedly faster than the core network, with security, digital authentication, analytics, and consulting cited as key contributors. This mix shift broadens growth beyond card payment fees and supports resilience.
Headway’s mission is a big one – to build a new mental health care system everyone can access. We’ve built technology that helps people find great therapists with the first software-enabled national network of providers accepting insurance. 1 in 4 people in the US have a treatable mental health condition, but the majority of providers don’t accept insurance, making therapy...
Headway's Top Stability & Growth Strengths
Market Expansion: National and payer footprint have broadened materially, with availability across all 50 states, plan relationships rising toward 100+, and sharp increases in providers, patients, and appointments. This widening reach indicates an ability to capture demand across geographies and insurance lines.
Investor Backing & Capital Strength: A $100M Series D at a roughly $2.3B valuation alongside substantial prior financing reflects strong access to growth capital. This position supports continued scaling of the network, product investments, and deeper insurer integrations.
Strong Revenue Growth: Revenue is described as having increased significantly over a recent 12‑month period, with earlier disclosures citing outsized year‑over‑year gains. Coupled with rising session volumes, this points to robust top‑line momentum despite limited public financial detail.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Profitability: Square gross profit increased year over year in 2025 and again in recent quarters, with gains driven by processing, software, and financial solutions like Square Loans. Filings indicate this momentum continued into 2026, with growth excluding hardware also improving.
Strong Market Position & Advantage: Square is described as a leader in small-business POS and commerce, serving millions of sellers and processing a very large volume of payments. Industry recognition and scale suggest durable competitive positioning in its core segments.
Market Expansion: International payment volume is growing faster than the U.S., and sectors such as food and beverage led recent gains. Seller acquisition accelerated late in 2025, indicating widening reach across geographies and customer segments.

People Inc. is America’s largest digital and print publisher. Our 40+ iconic and fast-growing brands harness the best intent-driven content, the fastest sites, and the fewest ads to help nearly 200 million people every month, including 95 percent of US women, make decisions, take action, and find inspiration. People Inc. brands include PEOPLE, Better Homes & Gardens, Verywell, FOOD &...

People Inc.'s Top Stability & Growth Strengths
Profitability: Digital operating income and adjusted EBITDA are rising, with margins improving (e.g., digital operating income up 56% in Q1 2026 and digital EBITDA margin expanding from 18% to 20%). Management also guided to mid‑to‑high single‑digit growth in digital adjusted EBITDA for 2026.
Strong Revenue Growth: Digital revenue shows a clear multi‑quarter uptrend: up 10% for full‑year 2025, +14% YoY in Q4 2025, +8% in Q1 2026, and +6% in Q2 2026. These gains indicate sustained momentum in the core digital segment despite broader headwinds.
Diversified Revenue Streams: Growth is coming from multiple digital lines—advertising, performance marketing, and licensing/other—and increasing revenue from sources less dependent on traditional website sessions. This mix shift helps offset pressure from search‑driven traffic declines.
We bring together clinical expertise, always-on tools, and deep insights so clients can improve their lives, providers can build practices they're proud of, and businesses can offer more effective, more efficient care. We believe mental health is a never-ending pursuit, and we build toward that progress every day. For our team, that means a day's work can literally change someone's life....

Grow Therapy's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is depicted as rising dramatically, including an increase from $3.6M in 2021 to $617.4M in 2024 and subsequent commentary citing a roughly $1B run rate.
Investor Backing & Capital Strength: Capital access appears robust, highlighted by a $150M Series D in 2026 at an approximately $3B valuation and total funding near $328M from prominent investors.
Market Expansion: Geographic and channel reach is expanding, with 26,000+ clinicians across all 50 states, 125+ insurance partners (including Medicare and Medicaid), and movement into employer and health‑system partnerships.
.jpg)
Metropolis Technologies, Inc. is an artificial intelligence company whose computer vision platform enables checkout-free payment experiences for the real world. Its proprietary AI-driven technology reaches more than 50 million customers while reducing costs, increasing transparency and capturing additional revenue for real estate partners. Following its take-private acquisition of SP+, Metropolis is now the largest parking network in North America with...

Metropolis Technologies's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investors and lenders have provided substantial capital to fund expansion, including a 2025 $1.6B package (~$500M Series D plus a $1.1B term loan) at an approximately $5B valuation. Earlier financings tied to the SP+ transaction added further resources to scale.
Strong Market Position & Advantage: Following the SP+ acquisition, the company is described as the largest parking operator/network in North America, with 4,000–4,600+ locations and more than $5B in annual transactions. External recognition such as CNBC Disruptor 50 and TIME100 listings reinforces its prominence in the category.
Market Expansion: The footprint and membership base have accelerated from roughly 600 facilities and 1M+ members in 2022 to 4,500+ locations and 20M–30M+ members, with 1M+ new members per month at times. Expansion beyond parking into retail, hospitality, fueling, aviation, and other mobility verticals is supported by acquisitions (SP+, Oosto) and rapid post‑merger site upgrades.

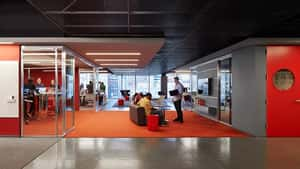
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Consolidated revenue has increased across recent years, with additional year-over-year gains extending into early 2026. This pattern indicates ongoing top-line expansion even as quarterly and annual growth rates vary.
Profitability: Operating income reached new highs in 2025 and continued to rise in subsequent quarters. This points to improving operating leverage alongside revenue growth.
Product Line Growth: Businesses such as Morningstar Credit, PitchBook, Retirement, and the Direct Platform are cited as key growth engines, with Credit standing out. This breadth of product contributions supports expansion beyond a single offering.

Possible Finance is on a mission to make financial health possible for everyone. We build products for the millions of Americans who live paycheck to paycheck, face unpredictable income, or can't get a fair shot from traditional banks and credit systems — people who are routinely ignored or penalized by mainstream financial institutions. That's why our products are designed differently. We...

Possible Finance's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have risen from 2024 to 2025, with an annualized run rate later surpassing the $125–$130 million range. This momentum is highlighted alongside increases in customer usage and overall scale.
Profitability: The company achieved its first annual net profit (around $3 million), indicating healthier unit economics and improving financial stability. This marks a shift from earlier periods focused on rebuilding.
Market Expansion: Operations expanded into 19 new states in 2025, bringing total coverage to roughly 33–34 states. New offerings such as Possible Advance further extended product reach and addressable market.
Hiya is trusted by global businesses, carriers, and consumers to enable secure, engaging connections and stop unwanted calls. Hiya is pioneering the next generation of AI-powered voice intelligence with real-time analysis and an AI assistant to enhance voice protection, productivity, and call performance. Hiya connects businesses with their customers, helps carriers secure their networks, and protects people from spam and...
Hiya Inc.'s Top Stability & Growth Strengths
Strategic Partnerships: Samsung and Hiya extended their relationship through 2028, and Hiya highlights deep integrations with major operators and OEMs. Recent launches with Vodafone (UK and Ireland), Bouygues Telecom (France), DNA Finland, Telenor Sweden, Deutsche Telekom and O2 Telefónica (Germany) reinforce embedded distribution at device and network level.
Market Expansion: Hiya reports coverage in 40+ countries with network reach growing from 200M+ in 2021 to 500M–550M+ people, alongside analysis of 28B+ calls per month. Ongoing European rollouts in 2025–2026 indicate continued geographic scaling and platform utilization.
Product Line Growth: The company has broadened beyond caller ID/spam blocking into enterprise SaaS and branded calling, introducing offerings such as Hiya AI Phone and Caller Reputation. The acquisition of Loccus.ai for deepfake voice detection further expands its voice‑security portfolio.
.png)
We bring people together around the things they love and turn their passions into their livelihood.

Whatnot's Top Stability & Growth Strengths
Strong Revenue Growth: Transaction metrics are reported as surging, with more than $8B in 2025 livestream sales that more than doubled 2024 and were already surpassed by mid-2026. Independent coverage also cites triple-digit year-over-year revenue growth and estimates around the $1B level.
Investor Backing & Capital Strength: Capital raises include a $545M Series G in August 2026 at a $20B valuation, up from $11.5B in late 2025. These valuation step-ups signal strong access to growth capital and investor confidence.
Strong Market Position & Advantage: Market position is portrayed as leading among live-shopping platforms in North America and Europe, with high engagement and more than 1 billion cumulative orders by June 2026. Ongoing expansion into new categories and AI-driven seller tools further reinforces competitive standing.

Launch, pivot, or accelerate your career with an organization invested in your success. Together, we’re transforming the homeownership journey and redefining what it means to serve clients with heart, innovation, and impact. At Redfin, your work will help make the dream of owning a home more accessible and equitable for everyone. You bring the relationships; we handle the rest. Our...

Redfin's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 7% in 2024 to $1.043B, with Q4 2024 up 12% year over year. Core brokerage revenue increased 5% and rentals grew 10% in 2024, underscoring broad-based top-line gains.
Strategic Partnerships: Integration with Rocket after July 2025 and a February 2026 arrangement with Compass expanded reach and cross-sell, with monthly active users up 3.3% YoY in March 2026. Digital purchase‑mortgage leads have grown more than 3× since the acquisition, indicating rising conversion potential.
Cost & Operational Efficiency: Expense synergies of approximately $140M were realized in less than six months post‑acquisition. This signals tangible efficiencies from integration.
tms unites technology and marketing and sourcing to drive transformational change for the world’s leading brands. With 1200+ employees across 26 countries, we offer an impressive range of solutions — from inspiration and innovation to category management and delivery. Headquartered in Chicago with 10 offices worldwide, we are responsible for some of the world’s most successful and iconic long-term marketing...

tms's Top Stability & Growth Strengths
Strong Hiring & Retention: Available information indicates headcount has moved from more than 900 to about 1,400 alongside active recruitment across marketing, design, engineering, and procurement, signaling ongoing talent expansion. Third‑party and campus postings in 2026 also reference 1,400+ employees across 26–28 countries.
Market Expansion: The organization operates across 26–28 countries with offices spanning North America, Europe, the Middle East, and Asia. This broad international footprint supports delivery across 100+ countries and multi‑market programs.
Strategic Partnerships: Continuing activity with major global clients such as McDonald’s, Starbucks, O2, Sony and others is evidenced by recent 2026 campaigns and long‑tenured relationships. The company also cites 400+ brand partnerships and large‑scale daily reach, indicating depth of commercial ties.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is presented as expanding substantially across fiscal 2026 and into fiscal 2027, with multiple consecutive quarters showing strong year-over-year increases. The momentum spans both total revenue and subscription metrics, indicating broad-based top-line expansion.
Healthy Cash Flow: Operating cash flow and free cash flow are described as improving markedly, moving from modest levels to solid positive generation. Recent results also point to expanding contribution margins, suggesting better unit economics as scale increases.
Customer Loyalty & Retention: Average subscription dollar-based net retention is noted as comfortably above the expansion threshold, implying existing customers are growing their spend. Growth in the cohort of customers generating at least $100K in subscription ARR reinforces durable land-and-expand dynamics.
Superhuman (formerly Grammarly) is the AI productivity platform on a mission to unlock the superhuman potential in everyone. The Superhuman suite of apps and agents brings AI wherever people work, integrating with over 1 million applications and websites. The company’s products include Grammarly’s writing assistance, Docs’ connected surface for teams, Mail’s inbox management, and Go, the proactive AI assistant that...
Superhuman's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Strategic capital is substantial, with $1B raised in 2025 to fund expansion into an AI productivity platform. This provides significant financial capacity for acquisitions and product development.
Product Line Growth: The company has broadened its footprint through acquisitions including Coda (now part of the suite), GPTZero, Rows, and Fathom, while integrating advanced AI capabilities like Superhuman Go and agent ecosystems. These moves expand the offering well beyond the original email client.
Market Expansion: Current materials cite 40M+ daily active users and 50K+ organizations, reflecting the larger Superhuman/Grammarly platform after the rebrand. Continued M&A in 2026 further extends reach into authenticity and meeting-productivity use cases.
Liberty Mutual Insurance exists to help people embrace today and confidently pursue tomorrow. A Fortune 100 company and global leader in property and casualty insurance, we’ve spent over a century creating innovative products, services and technologies to meet the world’s ever-changing needs and make a difference for our customers and communities.
Liberty Mutual Insurance's Top Stability & Growth Strengths
Profitability: Net income rose to $6.79B in 2025 from $4.38B in 2024. The combined ratio improved materially (e.g., S&P-adjusted 89.7% in 2025 and high-80s in early 2026), indicating stronger underwriting performance.
Investor Backing & Capital Strength: Shareholders’ equity increased from about $22.2B in 2022 to $39.9B at year-end 2025 and exceeded $44B by mid-2026. External ratings actions (AM Best A affirmation in Sept 2025; S&P upgrade to A+ in July 2026) underscore improved capitalization.
Resilient & Sustainable Growth: S&P describes deliberate portfolio reshaping and expects 2–3% annual premium growth during 2026–2028. Management emphasizes disciplined, selective expansion following underwriting improvements, prioritizing durable returns over sheer volume.
Carbon Robotics is the leader in physical AI for agriculture, helping farmers become more profitable and sustainable. Its flagship product, the LaserWeeder™, is the world’s leading commercial laser weeding system with hundreds of units operated by farmers in 15 countries worldwide. LaserWeeder combines computer vision, AI, robotics, and high-powered lasers to identify weeds and destroy them with sub-millimeter precision—no herbicides, hand...

Carbon Robotics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have doubled over the 12 months prior to October 2024 and later surpassed $100M annually for the fiscal year ending January 31, 2026. Subsequent commentary describes continued scaling beyond this milestone, indicating ongoing momentum.
Market Expansion: Operations are described as spanning roughly 15–20 countries with particularly strong traction in the U.S., Western Europe, and Australia, alongside manufacturing and service footprints in the U.S. and Europe. Customer adoption is cited as 200+ growers across 15 countries, signaling broadening geographic reach.
Product Line Growth: The company moved beyond LaserWeeder into Carbon Autonomy/AutoTractor and launched the LaserWeeder G2 line. Another agricultural robot in development and autonomy programs further indicate portfolio expansion.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.



